Written by
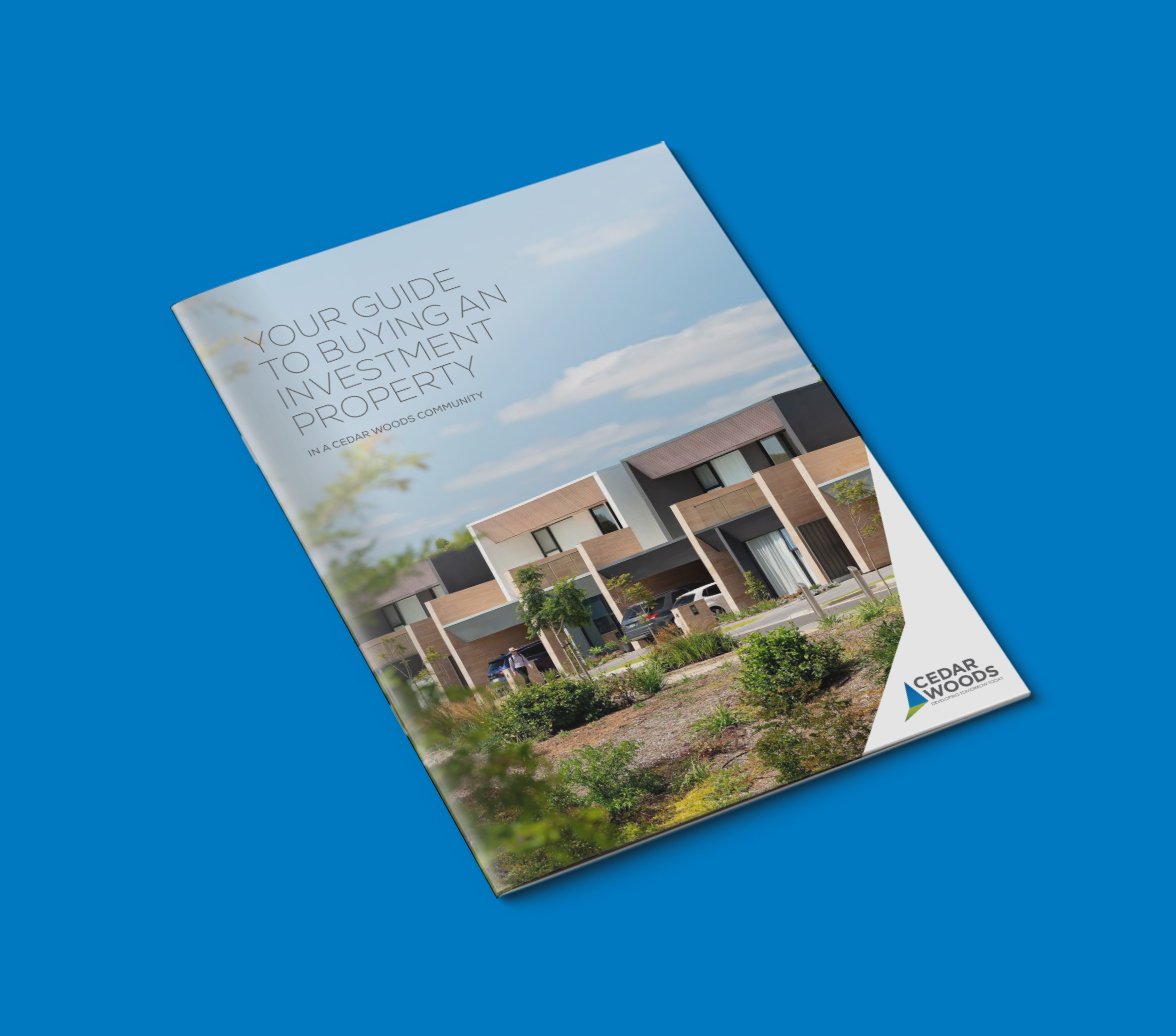
Your guide to buying an investment property

From 1 July 2027, Australia’s tax settings for residential property investment will change in a way that gives investors a stronger incentive to consider qualifying new housing.
Under legislation passed in June 2026, new restrictions will apply to negative gearing for residential investments from 1 July 2027. Investments made before 7:30 pm AEST on 12 May 2026 are protected from the new restrictions, while qualifying new residential dwellings can continue to be negatively geared.
Capital gains tax settings are also changing, with qualifying new residential property receiving different treatment under the new arrangements.
The Australian Government has said the reforms are intended to direct more private investment towards new housing rather than established homes.
For investors considering residential property, that makes the distinction between new and established housing more important than it has been previously.
It also makes it important to understand what qualifies as a new residential dwelling, how the negative gearing and CGT changes work, and what else should be considered before buying.
What is changing with negative gearing?
Negative gearing generally occurs when the deductible costs of holding an investment property are greater than the income the property earns.
Under the new rules, from the 2027–28 income year, new restrictions will apply to negative gearing for residential property.
Investments made before 7:30 pm AEST on 12 May 2026 are exempt from the new restrictions. Qualifying new residential dwellings can continue to be negatively geared.
For established residential property acquired after the announcement date, losses can still be deducted against other residential property income, including capital gains from residential property, and excess losses can be carried forward.
What changes is the ability to deduct those losses against non-residential income such as wages.
For an investor weighing up new and established property, that creates a significant difference in tax treatment.
What is changing with capital gains tax?
Capital gains tax settings are also changing from 1 July 2027.
For relevant capital gains accruing from that date, the existing 50 per cent CGT discount is being replaced by arrangements based on inflation-adjusted gains, while certain capital gains will also be subject to a minimum tax rate of 30 per cent.
Qualifying new residential property is treated differently.
Investors in qualifying new residential dwellings can retain access to the existing 50 per cent CGT discount or choose the new indexation treatment, subject to the applicable rules and their circumstances.
The legislation therefore gives qualifying new residential property different treatment under both negative gearing and CGT.
For investors, that makes the status of the property increasingly relevant not only while it is being held, but potentially when it is eventually sold.
Why does buying new matter more under the changes?
The reforms have been structured to direct more investor demand towards new housing.
The Government has said that more than 80 per cent of new investor lending has been going towards existing homes and that it wants more private investment supporting the construction of new supply.
The new tax settings are one way of creating that incentive.
An investor purchasing a qualifying new residential dwelling can potentially retain access to negative gearing while also having a choice of CGT treatment when the property is sold.
An investor purchasing affected established housing after the announcement date will not receive the same negative gearing treatment.
That does not mean a new property will automatically be the right investment for every buyer. Location, purchase price, rental demand, ongoing costs, expected holding period and individual financial circumstances still matter.
But from a tax perspective, the reforms make qualifying new residential property more relevant to investors considering where to direct their capital.
What counts as a new residential dwelling?
This is an important qualification.
The legislation establishes the framework for qualifying new residential dwellings, but the final detailed eligibility requirements are still being settled.
In August 2026, the Australian Government consulted on proposed rules under which a property would generally be considered new where it genuinely adds to housing supply and is acquired within 24 months of a certificate of occupancy being issued.
The proposal extended the 12-month period initially outlined in the Federal Budget.
The Government has subsequently indicated that the definition of eligible new builds will be addressed through a future tranche of tax reform legislation following consultation.
As at October 2026, the final eligibility requirements have therefore not yet been settled in law.
That means investors should not assume that a property qualifies for the new-build treatment simply because it is recently constructed or marketed as new.
The current rules and professional tax advice should be checked before relying on the tax treatment of a particular property.
What should investors consider when buying new property?
The tax changes make new residential property more relevant for investors considering their options, but tax treatment should sit alongside the fundamentals of the investment itself.
That includes the location, dwelling type, purchase and holding costs, likely rental demand, surrounding amenity, access to employment and transport, the local supply of comparable homes and how the property fits within the investor’s broader financial position.
Investors should also establish whether the property is expected to satisfy the final new-residential-dwelling requirements once those rules are settled.
A qualifying new build may receive different treatment under the new negative gearing and CGT settings, but that does not replace the need to assess whether the property itself is suitable for the investor.
Where does Cedar Woods fit?
Cedar Woods develops and sells new residential property rather than established resale housing.
That makes the shift in investor incentives towards new housing particularly relevant for people exploring opportunities within Cedar Woods communities. Depending on the project, product and current availability, investors can explore new residential opportunities across Cedar Woods’ portfolio.
Whether an individual property qualifies for the new tax treatment will depend on the final eligibility requirements and the circumstances of the purchase, so eligibility should be confirmed before an investment decision is made.
For investors already considering residential property, the reforms provide another reason to include new housing in their search.
What do the changes mean for home buyers?
Not everyone purchasing a new home is an investor.
For owner-occupiers, negative gearing and investment CGT treatment will generally not be the reason for choosing a property.
The reforms can still matter indirectly.
By directing tax incentives towards new residential investment, the policy is intended to encourage more private capital into new housing supply while reducing investor demand for established homes.
For people buying a home to live in, the usual considerations remain more important: location, housing type, budget, amenity, access to services and whether the home will suit their needs over time.
New housing can therefore serve different buyers for different reasons. Investors may be responding partly to the changing tax settings, while owner-occupiers may simply be looking for a new home that suits the way they want to live.
New housing and housing supply
The tax reforms are designed to encourage investment into new residential supply, but incentives alone do not create homes.
New housing still needs land, planning and approvals, infrastructure, construction capacity and coordinated delivery.
That is where new residential development plays a practical role.
By bringing new housing to market, developers can provide homes for owner-occupiers while also giving investors access to new residential property that may qualify for the Government’s new tax treatment.
Cedar Woods develops communities with a range of new housing options designed for different buyers and stages of life.
Explore new homes with Cedar Woods
If you are considering buying new property, explore Cedar Woods communities and the residential opportunities currently available.
Explore Cedar Woods Communities
This article provides general information only and does not constitute financial, tax or legal advice. Tax treatment depends on individual circumstances and applicable law. The eligibility requirements for new residential dwellings under the reforms are still being finalised. Buyers and investors should obtain independent professional advice before making property or investment decisions.